


2026 Year-End Tax Planning
As we near the end of the year there are some important year-end tax deadline reminders and tax strategies to consider. This ranges from the required IRA distributions, education reimbursements from 529s, charitable donations, contributions to certain account types and strategic Roth conversions. And while most OBBBA provisions were effective in 2025 and remain so this year, there are a few new ones for 2026. See my recent blog post for some key provisions of OBBBA.
This blog post will focus mainly on Federal taxes, not State. This is not formal tax advice and I am not an accountant. But as a financial planner, I understand these topics very well and perform detailed tax planning for our clients. This gives them more control and minimizes tax surprises next spring. Reach out if that sounds appealing.
Marginal Federal Tax Brackets for Income and Capital Gains
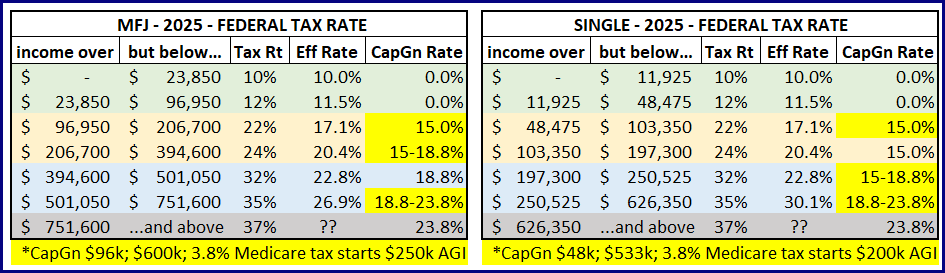
An important driver in assessing different tax strategies is “What is this worth?”. The answer lies in the type of taxable income impacted – ordinary income or capital gains (and qualified dividends) – and your marginal tax rate (how the next $1 of income is taxed). The table below shows income and capital gains tax rates for Single and Married Filing Jointly for 2026 tax year. The 2027 brackets have been published (3.25% higher EXCEPT lowest IRMAA band only up 2.75%... hmmm) but be sure to work off these 2026 numbers for planning. You can also reference my recent blog post describing key lines of your tax return.
Max out contributions for accounts with year-end deadlines
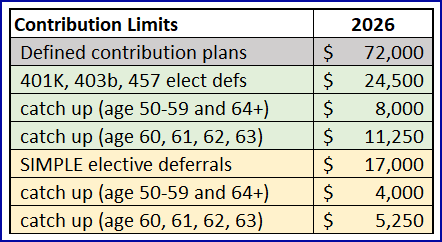
Some of the tax-favored accounts must have contributions done by year-end while others allow up to tax filing next spring (or later) that still apply to the 2026 tax year. Here are the most common accounts with year-end deadlines. Some of these account’s contributions come via payroll deductions so you can crank up the % contribution now, just be sure to adjust back in January to the annual run rate. Here are the 2026 contribution limits for some accounts mentioned below.
- 401k/3b Employee Contributions
- Traditional contributions deductible; Roth is not; starting in 2026, if prior year wages from same employer above $150k, catch-up must go to Roth 401k
- If working for company or self-employed with S-Corp, must make via payroll deductions by adjusting withholding
- If plan allows and max out 401k/3b, can also make “after-tax” contributions (different than Roth 401k/3b); ideally move to Roth IRA soon after contribution
- College Savings Plans (529s) – most of them anyway
- Contributions deductible at some states only, up to limits that vary by state; not deductible at Federal level
- Investment gains not taxed at Federal and State if for qualified education costs
- Fund Donor Advised Fund (DAF) if charitably inclined
- Deduction on full contribution current year, then future years’ donations from DAF not deductible but ideally in lower tax bracket
- If contribute appreciated securities can deduct full MV but avoid capital gains tax
- May allow for additional Roth conversions if done in same year but since deduction “below the line”, no help with Medicare IRMAA bands
- OBBBA Impacts – starting in ’26 first 0.50% of AGI excluded from deduction if itemize; max value of deduction capped at 35%
- Trump Accounts
- There may be better account types to contribute first; see recent blog post.
- If still think it makes sense, the $5,000 annual contribution limit must be done by year-end, unlike other IRAs (see next section).
Accounts where contributions can be made next spring for 2026 tax year
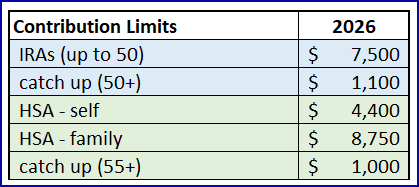
Some people like to make contributions as soon as possible, while others may need to confirm income to see if a contribution allowed, is deductible, or waiting for cash-flow to fund. Here is list of tax-favored accounts that allow contributions next spring for tax year 2026 along with contribution limits for 2026.
- Traditional and Roth IRAs
- whether deductible for Traditional or allowed for Roth depends on income
- Health Savings Accounts (HSAs)
- No income limits; must have High Deductible Heath Plan for tax year to contribute
- Self-employed as single-member LLC or Sole Proprietor 401ks
- Employer contributions into 401k/3b
- Handful of states allow 529 contributions
Accounts that may require a distribution before year-end
The above discussion described maximizing contributions. There are some accounts where distributions must be done before year-end or penalties may occur.
- 529 reimbursement
- Income tax-free if used for qualified education expense
- Must withdraw qualified education expenses in same calendar year incurred
- Flexible Spending Accounts (FSA) – both Health Care and Dependent Care
- Income tax-free if used for qualified expense
- Unlike HSA, these accounts are “use it or lose it” each year
- Many plans offer 2.5 month grace period for submitting claims and allow carryforward of $680 for Health Care; $0 for Dependent Care
- Required Minimum Distribution (RMD) from IRAs/401k/3b
- Own Roth IRA/401k/3b
- NONE
- Own Traditional IRA/401k/3b
- Must begin age 73 (was 70.5, then 72; those born 1960+ will be age 75)
- Can delay first RMD until April 1 following year but then have double RMD second year, so watch total income and bracket impact
- Ordinary income unless past non-deductible contributions (see Form 8606)
- Can use as Qualified Charitable Distribution if 70.5+; not for Roth convert
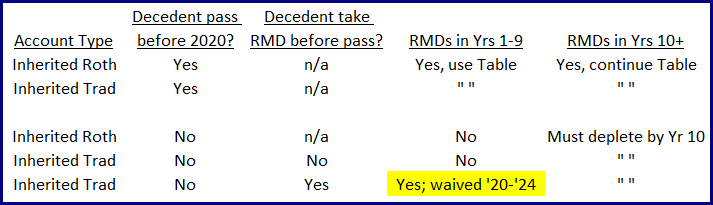
- Inherited Roth or Traditional IRA/401k/3b – YES INCLUDING ROTHs
- For this blog, I will not address rules for “eligible designated beneficiary” (spouse, minor children, disabled, chronically ill, less than 10 years younger)
- Ordinary income (see Form 8606); use RMD for QCD; no Roth conversions
- Allowed to take more than RMD without penalty and may want to for Traditional to manage taxable income over 10 years; ideally delay Roth
- Own Roth IRA/401k/3b
4. Qualified Charitable Distributions (QCD) for own or inherited IRA – NOT 401k/3b
- Only applies if above age 70.5; must wait until “.5”; age NOT changed like RMD
- Make direct contribution from IRA to qualified charity; counts toward RMD requirements above but QCD must be done before RMD taken out
- Maximum amount is $111,000 for 2026 (indexed to inflation starting in ‘24)
- Allows tax benefit for those not itemizing deductions; also reduces income for Medicare IRMAA (itemized deductions do not!); TELL ACCOUNTANT next spring
Itemized Deductions
Prior to 2025 many tax filers were taking the standard deduction since state and local tax (SALT – ie. State income tax and property tax) was capped at $10k. OBBBA allowed SALT deduction up to $40k provided Modified AGI was below $505k for 2026 (both Single and MFJ). If now itemizing, two categories are worth watching.
- You must incur any qualified medical expense which can be deductible for amounts above 7.5% of AGI
Charitable contributions must be made (directly or to DAF discussed above) by year-end. As mentioned above, the first 0.50% of AGI must be excluded from deduction and max value of deduction is capped at 35%.
NOTE OBBBA Impact starting in ’26: if take standard deduction, allowed to deduct up to $1k Single filer / $2k MFJ of cash charitable contributions made directly to charity.
Review realized capital gain/loss and search for harvesting – both losses and possibly gains
Recall gains from a security held more than one year is taxed at the lower capital gains rate; if less it counts toward ordinary income. Any losses offset gains - first short against short and long against long, then each other. If losses exceed gains, reduces ordinary income up to $3,000, then carry forward rest. Be careful with “wash sale rules” - can’t buy back same or substantially similar +/- 30 days, including spouse account if joint filer! If in 12% or lower income bracket (approximately), capital gains rate is 0% so may make sense to harvest gains but beware state tax may apply. Extra 3.8% Medicare tax kicks in at $200k / $250k AGI for Single / MFJ; extra 5.0% capital gains tax kicks in around $545k / $614k taxable income for Single / MFJ (see table at beginning of this post). Don’t forget about mutual fund distributions if held in taxable account. See funds’ websites for estimates or better yet, hold ETFs in these accounts! Finally, be aware that capital gains increases AGI which impacts many OBBBA triggers and Medicare IRMAA premiums.
Partial Roth Conversions
Roth conversions require a complicated analysis, not only estimates of current year taxable income (including all factors above) but also expected future taxable income, including Social Security and RMDs. Recall withdrawals not used for charity from Traditional IRAs and 401k/3b are taxed as ordinary income (states vary) unless past non-deductible contributions (see Form 8606). The concept is to convert part of a Traditional IRA/401k/3b into a Roth if in a lower or same tax bracket as expect to be in the future. A few of the complications to consider:
- Be aware of different income limits on deductions, contributions, tax credits, Medicare IRMAA, new OBBBA deductions including $6,000 Senior Exemption
- If lower income without Roth conversion and receiving Social Security, Roth conversion may force more Social Security income to be taxable (ranges from 0% - 85%)
- Ideally pay related tax from other account, not part of conversion; requires “estimated tax payment” with deadlines and may require accountant to use timing of income; DO NOT pay taxes as part of conversion if under age 59.5 as incurs 10% early withdraw penalty
- If age 63 or older, be aware of Medicare IRMAA premiums and how conversion impacts; yes, Medicare can start age 65 but IRMAA uses tax return from 2 years prior.
Review year-to-date tax withholdings vs. expected total taxes due and adjust
If you are still with me, you must really like tax planning so let’s get in the weeds here – ok, deeper in the weeds! Throughout the year you have taxes withheld from paycheck and/or paid via estimated tax payments due 4/15, 6/15, 9/15 and 1/15 of next year. To avoid a tax penalty (costs more recently with higher interest rates) you want at least the amount withheld that puts you in the “safe harbor” zone. If expect to fall short of “safe harbor”, update Form W4 with employer and specify extra dollar amount per paycheck (adjust back in Jan!) or pay estimated tax by 1/15 next year. Or if withholding too much (may happen if both spouses working and each employer assumes sole earner) adjust W4 as well! If doing an RMD or Roth conversion, you can also adjust the taxes withheld during that action. The nice thing about that approach is the tax was assumed to be paid throughout the year so the specific timing technique may not be required by accountant. That is not ideal for Roth conversion (DO NOT do this for Roth conversion if under age 59.5) if have taxable account to pay the taxes, but some like the “easy button”.
Who said taxes aren’t fun. Ok, maybe not fun, but there are plenty of actions one can take now rather than complaining about the large tax bill next spring. Grab your piece of the pie! Happy Thanksgiving!
Have questions? Reach out! We're happy to help.
Posted by Kirk, a fee-only financial advisor who looks at your complete financial picture through the lens of a multi-disciplined, credentialed professional. www.pvwealthmgt.com